SimplySAVE SBI Card Review
★ 3.5 / 5
At a Glance
| Joining Fee | ₹499 + GST (₹589 all-in) |
| Annual Fee | ₹499 + GST, reversed on ₹1 lakh annual spend |
| Best Suited For | First-time cardholders who spend mostly on groceries, dining and movies |
| Reward Type | Reward Points, redeemable against your card bill at 4 points = ₹1 |
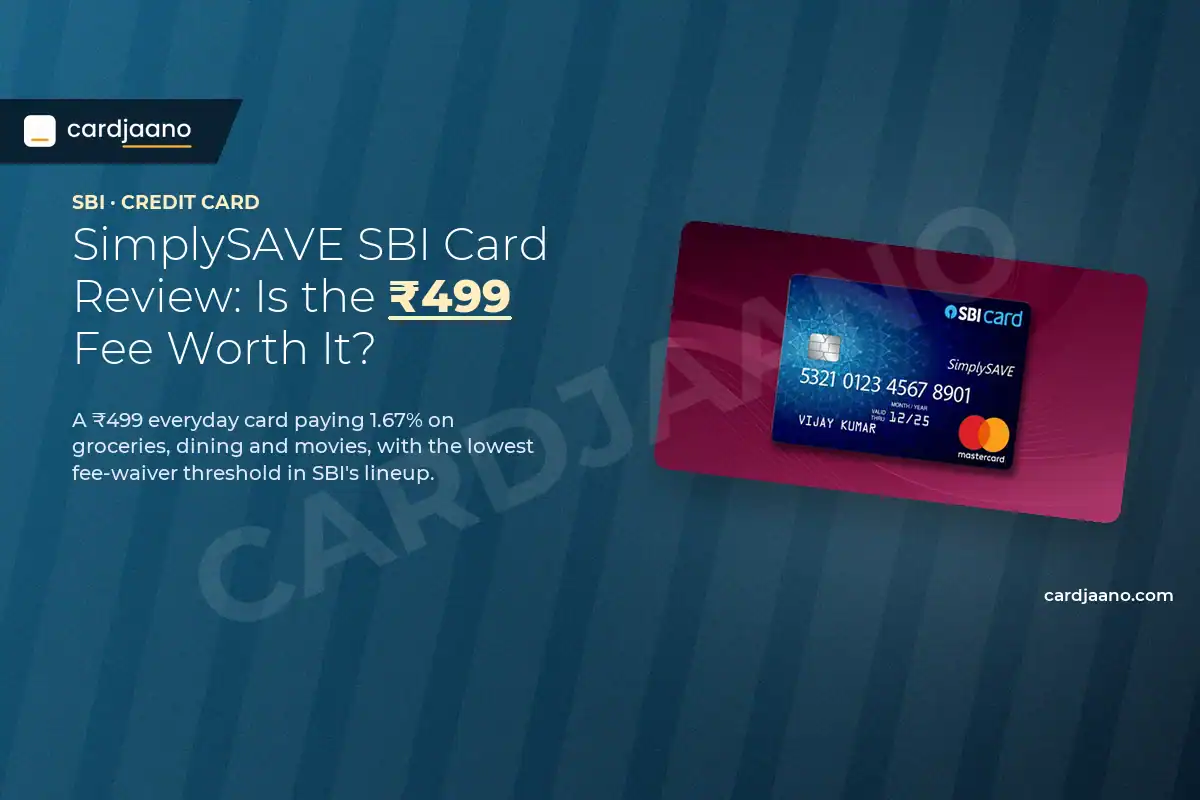
The SimplySAVE SBI Card is SBI Card’s entry-level everyday-spending card, and it does one thing well. It pays 10 Reward Points per ₹150 on dining, movies, groceries and departmental stores, which works out to 1.67% back in those four categories. That is competitive at a ₹499 fee. Everything outside them earns 1 Reward Point per ₹150, or 0.167%, which is close to nothing. So this is a card you hold for four merchant categories and not for general spending. The ₹1 lakh spend that reverses the renewal fee is the lowest waiver threshold across SBI’s lineup, and that is the quiet reason it works as a first card.
Rewards & Benefits
Reward rate and earn structure
| Spend category | Earn rate | Value back |
|---|---|---|
| Dining, movies, departmental stores, grocery | 10 Reward Points per ₹150 | 1.67% |
| All other retail spends | 1 Reward Point per ₹150 | 0.167% |
| Fuel | Nil | Nil |
SBI calls the accelerated rate “10X”, which is its way of saying 10 points instead of 1. The categories are decided by merchant category code, not by what the shop calls itself: departmental stores (5311), grocery stores and supermarkets (5411), restaurants (5812), drinking places (5813), fast food (5814) and motion picture theatres (7832). Food delivery apps and cinema booking apps frequently code as something else, so treat app spending as base rate until your statement proves otherwise.
The cap you need to know. Accelerated earning is limited to 5,000 Reward Points per calendar month across all four categories combined. You reach that at ₹75,000 of accelerated spending in a month, which most cardholders in this segment will never touch. Past the cap those categories drop to 1 point per ₹150 for the rest of the month. Fuel earns nothing at all, at any level, because MCCs 5172, 5541, 5542 and 5983 are excluded from the rewards programme entirely.
Note the ₹150 block, because it quietly costs you money. Points accrue on completed blocks of ₹150, so a ₹149 grocery bill earns zero and a ₹299 bill earns the same as a ₹150 one. On small, frequent transactions the drag is real.
Redemption and point value
Reward Points are redeemed against your outstanding card bill at 4 Reward Points = ₹1, which fixes a point at 25 paise. There is no transfer partner and no higher-value route, so the arithmetic never changes. Points are valid for 24 months from the date they are earned and are forfeited on the last day of the 24th month. You can also spend them in SBI’s rewards catalogue, though the statement-credit route is the one that reliably returns 25 paise a point.
Welcome benefit and the fee waiver
Spend ₹2,000 or more within your first 60 days and you get 2,000 bonus Reward Points, worth ₹500. That is a low bar, and it recovers most of the ₹589 all-in joining fee in year one.
From the second year the ₹499 renewal fee is reversed once your annual spending crosses ₹1 lakh, which is ₹8,334 a month. On a card built around groceries and dining that is achievable for most households, and it is the single most important number on this page. Clear it and the card is effectively free.
Worked example. On ₹1.5 lakh a year, split ₹60,000 across the accelerated categories and ₹90,000 elsewhere, you earn 4,000 points on the first and 600 on the second: 4,600 points worth ₹1,150, with the renewal fee reversed. That is an effective 0.77% overall, and 1.67% on the part of your spending the card was designed for.
Fuel surcharge waiver and everyday extras
| Benefit | Detail |
|---|---|
| Fuel surcharge waiver | 1% on transactions of ₹500 to ₹3,000, capped at ₹100 per statement cycle |
| Add-on cards | Free, for parents, spouse, children or siblings above 18 |
| Flexipay EMI | Available on transactions of ₹2,500 and above |
| Contactless payments | Tap and pay enabled |
| Acceptance | Visa or Mastercard, over 24 million outlets worldwide |
| Secured variant | SimplySAVE Advantage, issued against a fixed deposit |
The fuel waiver is worth up to ₹1,200 a year if you fill up in the ₹500 to ₹3,000 band every cycle, and it is the only fuel benefit here. Fuel spends earn no Reward Points, so do not treat this card as a fuel card.
Fees & Charges
| Charge | Amount |
|---|---|
| Joining fee | ₹499 + GST (₹589 all-in) |
| Renewal fee, per annum | ₹499 + GST, reversed on ₹1 lakh annual spend |
| Add-on card fee | Nil |
| Foreign currency markup | 3.5% |
| Dynamic currency conversion | 3.5% |
| Finance charges | 3.75% per month, 45% per annum |
| Cash advance fee | 2.5% of the amount or ₹500, whichever is higher |
| Late payment charge | Nil up to ₹100 outstanding, then ₹100, ₹500, ₹750, ₹950, ₹1,100, rising to ₹1,300 above ₹50,000 |
| Overlimit fee | 2.5% of the overlimit amount or ₹600, whichever is higher |
| Payment dishonour fee | 2% of the payment amount, minimum ₹500 |
| Rent payment processing fee | ₹199 per transaction |
| Utility payment fee | 1% if utility spends cross ₹50,000 in a billing cycle |
| Wallet load fee | 1% on every wallet load above ₹1,000 |
| Education payment fee | 1% of the transaction amount |
| Card replacement fee | ₹100 to ₹250 |
| Fuel surcharge waiver | 1% on transactions of ₹500 to ₹3,000, capped at ₹100 per statement cycle |
Hitting the ₹1 lakh waiver. The reversal is assessed on your annual spending in the preceding year, and cash advances do not count towards it. At ₹8,334 a month it is the easiest waiver SBI offers, and the practical way to clear it is to route groceries and dining through this card and let the accelerated categories do the work. If your yearly spending sits below ₹1 lakh, budget for ₹589 every year.
The charge that catches people out. The 1% utility fee applies to the whole month’s utility total once it crosses ₹50,000 in a billing cycle, not just the excess, so a ₹52,000 month costs ₹520 on spending that earns 0.167%. Rent at ₹199 a transaction and wallet loads above ₹1,000 at 1% work the same way. Keep rent, utilities and wallet top-ups off this card.
Eligibility & Documents Required
SBI Card does not publish a fixed minimum income for the SimplySAVE. Its own product record places the card in the ₹1,000 to ₹49,000 monthly income bracket, which is the lowest band in SBI’s range and confirms the card is aimed at entry-level applicants. A secured variant, the SimplySAVE Advantage, is issued against a fixed deposit for applicants who cannot meet the unsecured criteria.
| Criterion | Requirement |
|---|---|
| Age | 18 years and above |
| Nationality | Indian resident |
| Income | No fixed minimum published; positioned for the ₹1,000 to ₹49,000 monthly band |
| Credit score | No published minimum; a clean repayment record improves your odds |
Documents: PAN, identity proof such as Aadhaar or passport, address proof, and income proof in the form of salary slips, Form 16, or audited returns if you are self-employed. Approval is at SBI Card’s discretion.
Pros & Cons
| Pros | Cons |
|---|---|
| 1.67% back on dining, movies, grocery and departmental stores | 0.167% base rate is among the weakest of any paid card |
| ₹1 lakh fee waiver, the lowest threshold in SBI’s lineup | Points are fixed at 25 paise with no transfer partners |
| ₹500 welcome bonus on just ₹2,000 of spending in 60 days | The ₹150 earning block wastes value on small bills |
| Accelerated cap of 5,000 points a month is generous for the segment | Fuel earns no points at all |
| Free add-on cards and a secured variant for thin credit files | 3.5% forex markup makes it unsuitable for travel |
| Low ₹499 fee keeps the break-even easy to clear | No lounge access, no milestone bonuses, no insurance cover |
SimplySAVE SBI Card vs Competitors
| SimplySAVE SBI Card | SimplyCLICK SBI Card | CASHBACK SBI Card | |
|---|---|---|---|
| Annual fee | ₹499 + GST | ₹499 + GST | ₹999 + GST |
| Fee waiver | ₹1 lakh spend | ₹1 lakh spend | ₹2 lakh spend |
| Accelerated earn | 10 points / ₹150 on dining, movies, grocery, departmental stores | 10X on partner online brands, 5X on other online spends | 5% cashback on online spends |
| Base earn | 1 point / ₹150 | 1 point / ₹100 | 1% cashback offline |
| Welcome benefit | 2,000 points on ₹2,000 in 60 days | ₹500 Amazon voucher | None |
| Milestones | None | ₹2,000 vouchers at ₹1 lakh and ₹2 lakh online spend | None |
| Best for | Offline grocery and dining | Online shoppers | Broad online spending |
The real comparison is with SimplyCLICK, which costs exactly the same and waives its fee at the same ₹1 lakh. Pick SimplySAVE if your spending happens at supermarkets, restaurants and cinemas. Pick SimplyCLICK if it happens on Swiggy, Myntra and BookMyShow, since it also carries a better base rate of 1 point per ₹100. If you spend heavily online and can clear ₹2 lakh a year, the CASHBACK SBI Card at 5% beats both, but its ₹999 fee needs more spending to justify.
How to Apply
- Open the SimplySAVE SBI Card page on sbicard.com and select Apply Now.
- Fill in your personal, residential, employment and PAN details.
- Confirm your mobile number with the OTP.
- Upload identity, address and income proof.
- Complete video KYC, or wait for an SBI Card representative to arrange verification in person.
- Note the application reference number and track it on sbicard.com.
You can also apply through the ILA chatbot, at any SBI branch, or by calling the SBI Card helpline on 39 02 02 02 with your city STD code prefixed. Make a transaction of ₹2,000 or more within 60 days of approval to trigger the 2,000 bonus points.
Frequently Asked Questions
Is the SimplySAVE SBI Card annual fee waived? Yes, on ₹1 lakh of annual spending in the preceding year the ₹499 + GST renewal fee is reversed. The ₹499 joining fee in year one is not waived, but the ₹500 welcome bonus covers most of it.
What is the 10X reward on the SimplySAVE SBI Card? It is 10 Reward Points per ₹150 on dining, movies, grocery and departmental store spends, worth 1.67%, capped at 5,000 points in a calendar month. After the cap those categories earn 1 point per ₹150.
How much is one SimplySAVE Reward Point worth? Twenty-five paise. Four points redeem against ₹1 of your outstanding card bill, and there is no higher-value redemption route on this card.
What is the minimum salary for the SimplySAVE SBI Card? SBI Card does not publish a fixed income requirement. Its own product data places the card in the ₹1,000 to ₹49,000 monthly income band, the entry level of its range. You need to be an Indian resident aged 18 or above with income proof.
Does the SimplySAVE SBI Card give lounge access? No. There is no domestic or international lounge access on this card. For lounge visits from the same issuer you need SBI Card PRIME or higher.
Do fuel spends earn points on the SimplySAVE SBI Card? No. Petrol pump merchant codes are excluded from the rewards programme. You still get the 1% fuel surcharge waiver on transactions of ₹500 to ₹3,000, capped at ₹100 a statement cycle.
When do SimplySAVE Reward Points expire? Twenty-four months from the date they are earned. Unused points are forfeited on the last day of the 24th month, so redeem at least once every two years.
Bottom Line
The SimplySAVE SBI Card is a narrow card that is honest about being narrow. At ₹499 with a ₹1 lakh waiver and 1.67% on groceries, dining, movies and departmental stores, it is one of the least demanding paid cards in India to break even on. Treat it as a supermarket and restaurant card, keep a second card for everything else, and it earns its place.
Skip this card if most of your spending is online, if you travel abroad, or if you want lounge access, milestones or insurance cover, because this card has none of them and the 0.167% base rate punishes general use. Online spenders are better served by SimplyCLICK at the same fee, and anyone clearing ₹2 lakh a year should look at the CASHBACK SBI Card instead.
2 Comments