PNB RuPay Platinum Credit Card Review
At a Glance
| Joining Fee | Nil |
| Annual Fee | ₹500 + GST (₹590 all-in), waived if you use the card at least once in every quarter of the previous year |
| Best Suited For | PNB customers looking for a first credit card with UPI payments and a few lounge visits |
| Reward Type | PNB Reward Points, 1 point = ₹0.25 |
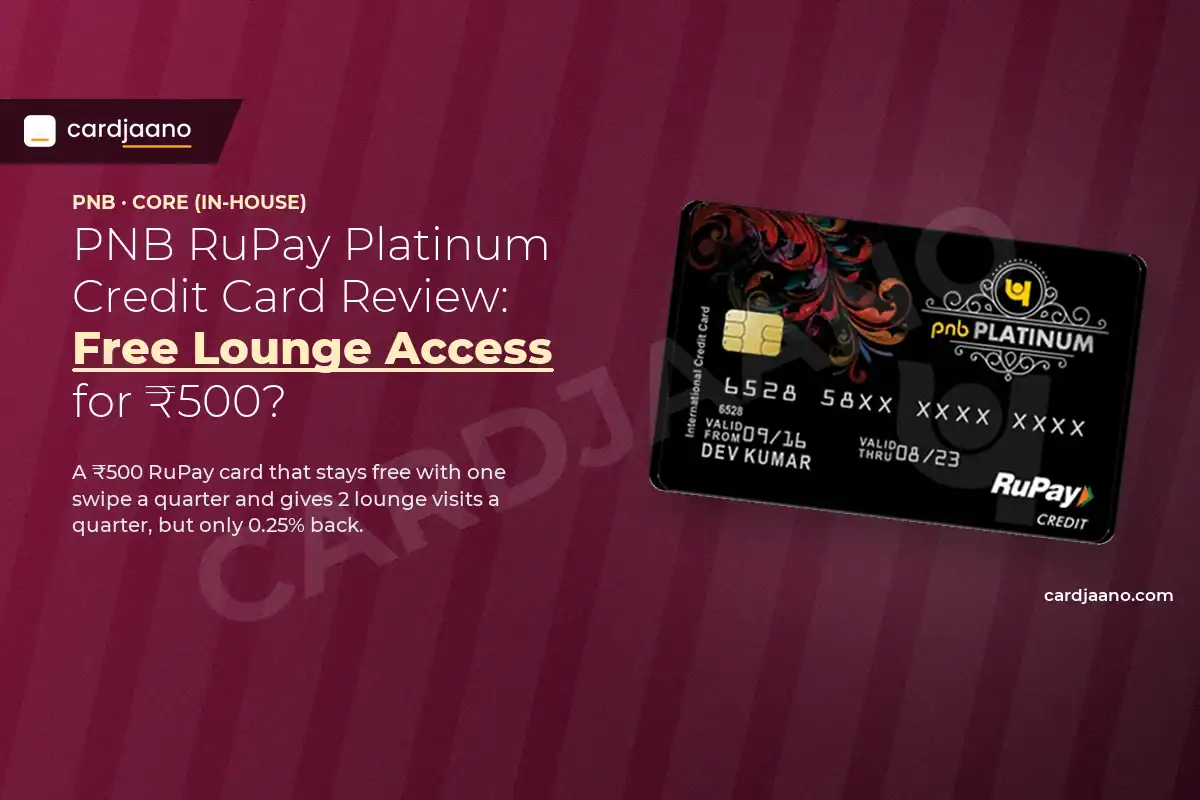
The PNB RuPay Platinum Credit Card is Punjab National Bank’s entry-level card. It has no joining fee, asks for an annual income of just ₹2.5 lakh, and its ₹500 annual fee goes away if you swipe it once a quarter.
Being a RuPay card, you can link it to UPI apps and pay at merchant QR codes. It also offers 2 domestic lounge visits a quarter, which is rare at this price.
The rewards are thin, though, at 0.25% back, and several of its charges go up from 1 November 2026. This review covers both.
Rewards & Benefits
Reward rate and earn structure
The card earns 1 Reward Point for every ₹100 spent, with no accelerated category; PNB’s product page lists the reward multiplier as “NA”, and it publishes no monthly cap on points.
With each point worth ₹0.25, that is 0.25% back: ₹1 lakh of spending a year earns 1,000 points, or ₹250. PNB’s MITC says reward points earned on a purchase are reversed if you later convert it into an EMI.
Redemption and point value
You redeem through PNB’s rewards portal, in blocks of at least 1,000 points. Each point is worth ₹0.25, so the smallest redemption is worth ₹250, and PNB charges ₹99 + GST per redemption request (about ₹117 all-in).
That fee takes almost half of a 1,000 point redemption, so wait until you have several thousand points before you redeem.
Welcome benefit
You get 300 bonus Reward Points (worth ₹75) on your first swipe, made within 90 days of receiving the card.
Travel, fuel and protection
| Benefit | Allowance |
|---|---|
| Domestic airport lounges | 2 visits a quarter |
| International airport lounges | 2 visits a year |
| Railway lounges | Not offered |
| Fuel surcharge waiver | 1% on fuel spends between ₹400 and ₹4,000, up to ₹350 a billing cycle |
| Personal accident cover | ₹2,00,000 |
| UPI | Card can be linked to UPI apps |
| Add-on cards | Free to join and free every year |
GST on the fuel surcharge is not waived, only the 1% surcharge itself. RuPay card offers also run through the year on the RuPay offers site.
Fees & Charges
PNB’s MITC revises several charges from 1 November 2026, so both columns are shown.
| Item | Until 31 October 2026 | From 1 November 2026 |
|---|---|---|
| Joining fee | Nil | Nil |
| Annual fee | ₹500, waived on quarterly use | ₹500, waived on quarterly use |
| Cash withdrawal, PNB ATMs | 2% or ₹100, whichever is higher | 2.5% or ₹400, whichever is higher |
| Cash withdrawal, other ATMs | 2% or ₹150, whichever is higher | 2.5% or ₹500, whichever is higher |
| Cash withdrawal, overseas | 2% or ₹250, whichever is higher | 2.5% or ₹500, whichever is higher |
| Late payment, total due up to ₹500 | Nil | Nil |
| Late payment, ₹501 to ₹1,000 | Nil | ₹500 |
| Late payment, ₹1,001 to ₹5,000 | ₹500 | ₹750 |
| Late payment, ₹5,001 to ₹10,000 | ₹600 | ₹750 |
| Late payment, ₹10,001 to ₹50,000 | ₹750 | ₹1,000 |
| Late payment, above ₹50,000 | ₹750 | ₹1,200 |
| Payment return | ₹200 | 2% of the payment, minimum ₹400 |
| Utility payments | No fee | 1% if utility spends top ₹50,000 a cycle, maximum ₹2,000 a transaction |
| Other charges | Amount |
|---|---|
| Interest | 2.95% a month, 35.89% a year |
| Interest-free period | 20 to 50 days, on purchases only |
| Foreign currency markup | 3.5% |
| Over-limit | 2.5% of the over-limit amount, minimum ₹500 |
| Railway tickets | 2.5% at the counter, up to 1.8% on IRCTC |
| Minimum Amount Due | 5% of the total due |
| GST | 18% on fees, interest and charges |
Keeping the card free is easy: make at least one purchase in each quarter of the year, and the ₹500 fee is waived.
PNB counts quarters from April, so put a small spend on the card in each of April to June, July to September, October to December and January to March.
The charge that catches people out is cash withdrawal. From 1 November 2026, taking even ₹2,000 from a PNB ATM costs ₹400 + GST, a fee of 20%, and interest at 2.95% a month starts from the day you withdraw.
Treat the cash limit, which is 20% of your credit limit, as an emergency option only.
Eligibility & Documents Required
PNB asks for an annual income of ₹2.5 lakh or more. The product page does not publish an age band or minimum credit score, so check the full criteria with PNB before applying.
Expect to provide PAN, address proof and income proof. You can apply online or through a PNB branch, and you may be asked to complete video KYC.
Pros & Cons
| Pros | Cons |
|---|---|
| No joining fee, annual fee waived on quarterly use | Only 0.25% back in reward points |
| 2 domestic lounge visits a quarter | 3.5% forex markup |
| Works with UPI as a RuPay card | Cash withdrawal fee rises to ₹400 minimum from November 2026 |
| Low ₹2.5 lakh income requirement | ₹99 + GST fee on each redemption |
PNB RuPay Platinum vs Competitors
| Card | Annual fee | Fee waived at |
|---|---|---|
| PNB RuPay Platinum | ₹500 + GST | One use each quarter |
| SimplySAVE SBI Card | ₹499 + GST | ₹1 lakh a year |
| HDFC Bank MoneyBack | ₹500 + GST | ₹50,000 a year |
All three cost about the same, but the PNB card is the easiest to keep free and the only one of these with lounge access.
The SBI and HDFC cards earn more on everyday categories such as groceries and online shopping, as our reviews show.
How to Apply
Apply on PNB’s credit card portal through the online or paperless application, or ask at your PNB branch. Pre-qualified PNB customers may see an offer when they log in.
Fill in your income and KYC details, complete video KYC if asked, and track the application on PNB’s portal. Once the card arrives, make your first purchase within 90 days to collect the 300 bonus points.
Frequently Asked Questions
Is the PNB RuPay Platinum annual fee waived?
Yes. The ₹500 annual fee is waived if you used the card at least once in every quarter of the previous year. Add-on cards carry no fee at all.
How many lounge visits does PNB RuPay Platinum give?
2 domestic airport lounge visits a quarter and 2 international visits a year. There is no railway lounge access.
What is the minimum salary for PNB RuPay Platinum?
₹2.5 lakh a year. Approval and credit limit depend on PNB’s assessment of your profile.
Can I use the PNB RuPay Platinum card on UPI?
Yes. It is a RuPay card, so you can link it to a UPI app and pay at merchant QR codes.
What is the forex markup on PNB RuPay Platinum?
3.5% of the transaction value, plus GST. That makes it a poor choice for spending abroad or on foreign websites.
Bottom Line
Get the PNB RuPay Platinum Credit Card if you bank with PNB, want an easy first card to build a credit history, and like the idea of a few free domestic lounge visits and UPI payments without paying a fee.
Using it once a quarter keeps it free. Skip it if you want rewards that add up, because 0.25% back is among the lowest in the market, and skip it for travel abroad, where the 3.5% markup bites. Never use it for cash from November 2026.
One Comment