HDFC Titanium Edge Credit Card Review
At a Glance
| Joining Fee | Not published on the product page |
| Annual Fee | Amount not published. Renewal fee is waived on spends of ₹50,000 within a year |
| Best Suited For | Existing holders with modest spends who want a no-frills card with a fuel surcharge waiver |
| Reward Type | Reward Points, redeemed as cashback at 100 points = ₹10 |
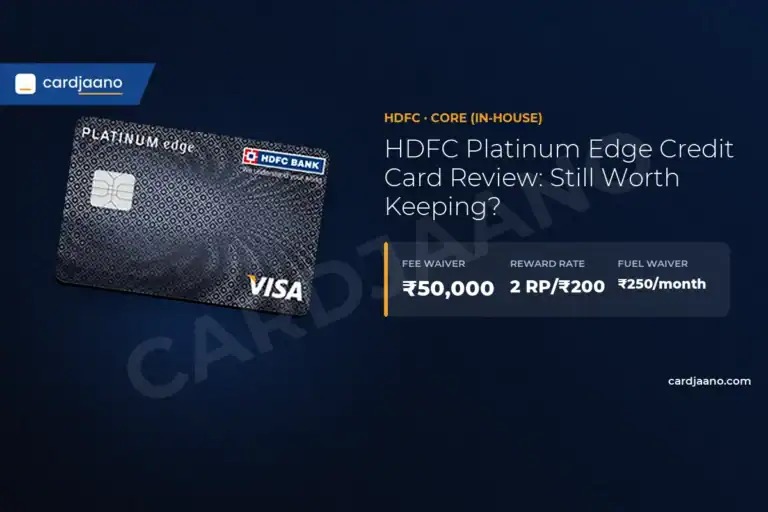
The HDFC Bank Titanium Edge is a basic entry-level rewards card with a 2 points per ₹200 earn, a 100% fuel surcharge waiver and a fee waiver that starts at ₹50,000 of yearly spends. HDFC’s own page says sourcing of this card has been stopped, so new customers cannot get it.
If you already hold one, the question is whether the low return justifies keeping it. At roughly 0.1% back on everyday spends, the answer depends almost entirely on the fuel waiver and on whether you pay a renewal fee at all.
Rewards & Benefits
Reward rate and earn structure
| Spend category | Benefit | Cap |
|---|---|---|
| Retail spends | 2 Reward Points per ₹200 | Cap not stated on the product page |
| Dining | 50% more Reward Points | Cap not stated on the product page |
| Utility bills and mobile recharges via PayZapp | Extra CashBack and Reward Points | Terms set by the PayZapp offer |
| Fuel | 100% fuel surcharge waiver | Maximum waiver of ₹250 per statement cycle |
The base earn works out to 1 point per ₹100. With dining at 50% more, you get 3 points per ₹200 at restaurants.
Redemption and point value
HDFC states that 100 Reward Points = ₹10 when you redeem for cashback against your outstanding card amount.
That makes one point worth ₹0.10. Spend ₹200 and you earn 2 points, or ₹0.20, which is a return of 0.1%.
Spend ₹1 lakh in a year and you earn about 1,000 points, worth ₹100. This is the weakest part of the card: the rewards are more of a courtesy than a reason to use it.
Fuel, safety and PayZapp benefits
| Fuel surcharge waiver | 100%, up to ₹250 per statement cycle |
| Interest-free period | Up to 50 days from the date of purchase |
| PayZapp offer | ₹1,000 CashBack on in-app shopping across 200+ brands |
| Contactless payments | Enabled, no PIN needed up to ₹5,000 a transaction in India |
| Fraud protection | EMV chip, zero liability on a lost card if reported immediately |
The fuel waiver is the most useful feature. Fuel surcharge is usually 1% of the transaction, so to use the full ₹250 in a cycle you would need to spend ₹25,000 on fuel that month.
For most holders the waiver will be a small, steady saving rather than the full amount.
Fees & Charges
| Joining fee | Not published on the product page |
| Annual (renewal) fee | Amount not published on the product page |
| Renewal waiver | Spends of ₹50,000 within a year |
| Interest on unpaid balance | 3.49% per month (41.88% a year) |
| Cash advance fee | 2.5% of the amount, minimum ₹500 |
| Interest-free period | Up to 50 days from the date of purchase |
| Fuel surcharge waiver | 100%, up to ₹250 per cycle |
To get the renewal fee waived you need about ₹4,200 of spends a month, which is an easy bar to clear.
Put your regular bills and groceries on the card and the fee should not bite. Your statement and the HDFC schedule of charges show the exact renewal amount for your card.
The charge that catches people out is the interest rate. At 3.49% a month, carrying even a small balance wipes out years of rewards.
A ₹10,000 balance costs about ₹349 for a month, against roughly ₹10 earned as points on the same spend.
Eligibility & Documents Required
HDFC does not publish income or age criteria on the Titanium Edge page, and it is not accepting new applications. Existing holders do not need to reapply.
For any current HDFC card, expect to provide identity proof, address proof and income proof such as salary slips or an ITR.
Pros & Cons
| Pros | Cons |
|---|---|
| 100% fuel surcharge waiver, up to ₹250 a cycle | Closed to new applicants |
| Renewal fee waived at only ₹50,000 spends | Base return is about 0.1% at ₹0.10 per point |
| Contactless payments and PayZapp cashback | Renewal fee amount is not published |
| Up to 50 days interest-free | 3.49% monthly interest if you revolve |
Titanium Edge vs Competitors
Titanium Edge sits at the bottom of HDFC’s old range, and it is closed. Today’s entry-level cards from HDFC and other banks usually offer flat cashback or a higher base earn with a similar low waiver threshold.
If you hold the Titanium Edge and have a cashback card with a better rate, move your main spends there and keep this one only if it costs you nothing.
How to Apply
You cannot. HDFC Bank states it is not accepting new applications for the Titanium Edge. Existing customers can manage the card through NetBanking, the MobileBanking app, MyCards, PayZapp or WhatsApp Banking.
For a new HDFC card, browse the bank’s current range on its official site.
Frequently Asked Questions
Can I still apply for the HDFC Titanium Edge credit card?
No. HDFC Bank says sourcing of the card has been stopped and it is not accepting new applications. Existing customers keep their benefits.
How do I get the Titanium Edge renewal fee waived?
Spend ₹50,000 within a year. That is about ₹4,200 a month. HDFC does not publish the renewal fee amount on the product page.
How many Reward Points does the Titanium Edge earn?
It earns 2 Reward Points for every ₹200 spent, with 50% more points on dining. HDFC states 100 points = ₹10 for cashback redemption.
What is the fuel surcharge waiver on the Titanium Edge?
It is a 100% waiver of the fuel surcharge, with a maximum of ₹250 per statement cycle.
What is the interest rate on the Titanium Edge?
The rate is 3.49% per month on any unpaid balance carried past the due date, which is about 41.88% a year.
What is the cash advance fee?
It is 2.5% of the amount withdrawn, with a minimum of ₹500, on every cash withdrawal.
Does the Titanium Edge support contactless payments?
Yes. In India, contactless payments up to ₹5,000 do not need a PIN for a single transaction.
Bottom Line
Keep the Titanium Edge if you already hold it, spend at least ₹50,000 a year and mainly want the 100% fuel surcharge waiver at no cost.
Skip it as a main card: it returns about 0.1% on retail spends, it is closed to new applicants, and the 3.49% monthly interest punishes any balance you carry. Anyone who spends heavily, wants lounge access or wants real rewards should look at a different card.