PNB Visa Classic Credit Card Review
At a Glance
| Joining Fee | Nil, for the primary card and add-on cards |
| Annual Fee | Nil, with no spend condition |
| Best Suited For | First-time borrowers who want a free, low-limit card to build a credit history with PNB |
| Reward Type | PNB Reward Points, 1 point = ₹0.25 |
The PNB Visa Classic Credit Card is Punjab National Bank’s most basic card. It has no joining fee and no annual fee, and PNB attaches no spend condition to either. You pay nothing to keep it, year after year.
It asks for an annual income of just ₹2.5 lakh, and credit limits run from ₹10,000 to ₹1 lakh. That makes it a realistic first card for someone with little or no credit history.
The trade-off is that it gives very little back. This review covers the 0.25% reward rate, the revised charges that apply from 1 November 2026, and how it compares with PNB’s other entry cards.
Rewards & Benefits
Reward rate and earn structure
The card earns 1 Reward Point for every ₹100 spent. PNB’s product page lists the reward multiplier as “NA”, so there is no accelerated category, and PNB publishes no monthly cap on points.
With each point worth ₹0.25, that is 0.25% back. ₹1 lakh of spending a year earns 1,000 points, worth ₹250. PNB’s MITC says points on a purchase are reversed if you later convert it into an EMI.
There is no welcome bonus either. PNB’s rewards page lists 300 bonus points on the first transaction only for its RuPay cards, not for Visa Classic.
Redemption and point value
| Redemption rule | Detail |
|---|---|
| Value of 1 point | ₹0.25 |
| Minimum redemption | 1,000 points (₹250) |
| Redemption fee | ₹99 + GST per request |
| Point validity | 3 years from the date earned |
| Where to redeem | PNB Rewardz portal, the toll-free line or a written request |
The ₹99 fee works out to about ₹117 with GST, almost half of a minimum 1,000 point redemption. Let points build to several thousand before you redeem.
On the PNB Rewardz portal you can pick movie tickets, hotel bookings, mobile and DTH recharges, merchandise and e-vouchers.
Points expire 3 years after they are earned, so a low spender has time to build up a balance worth redeeming.
Fuel, offers and other benefits
| Benefit | Detail |
|---|---|
| Fuel surcharge waiver | 1% on fuel spends from ₹400, up to ₹350 per billing cycle |
| Visa offers | Network offers on the Visa offers site |
| Airport and railway lounges | Not offered |
| Add-on cards | Free to join and free every year |
| Contactless payments | Up to ₹5,000 per transaction |
PNB’s fuel page lists the Visa Classic slab as ₹400 to ₹3,000 a transaction. Its revised Key Fact Statement from 1 November 2026 shows ₹400 to ₹4,000, so keep single fuel bills under ₹3,000 to be safe. GST on the surcharge is not refunded.
Fees & Charges
PNB’s revised Key Fact Statement applies from 1 November 2026, and the figures below are the new ones.
| Charge | Amount |
|---|---|
| Joining fee | Nil |
| Annual fee | Nil |
| Interest rate | 2.95% a month (35.89% a year) |
| Interest-free period | 20 to 50 days, on purchases only |
| Cash advance fee, PNB ATMs | 2.5% or ₹400, whichever is higher |
| Cash advance fee, other ATMs and overseas | 2.5% or ₹500, whichever is higher |
| Late fee, total due up to ₹500 | Nil |
| Late fee, ₹501 to ₹1,000 | ₹500 |
| Late fee, ₹1,001 to ₹10,000 | ₹750 |
| Late fee, ₹10,001 to ₹50,000 | ₹1,000 |
| Late fee, above ₹50,000 | ₹1,200 |
| Over-limit fee | 2.5%, minimum ₹250 |
| Payment return | 2% of the payment, minimum ₹400 |
| Utility payments | 1% if utility spends top ₹50,000 a cycle, maximum ₹2,000 a transaction |
| Foreign currency markup | 3.5% |
| Reward redemption | ₹99 per request |
| Card replacement | ₹100 |
| Minimum Amount Due | 5% of the total due |
All charges attract 18% GST. There is no fee to waive, so you do not need to hit any spend target. Cash withdrawals are capped at 20% of your credit limit.
The charge that catches people out is the cash advance fee. From 1 November 2026, taking ₹2,000 from a PNB ATM costs ₹400 + GST, which is 20% of the amount, and interest at 2.95% a month starts on the day of withdrawal.
The late fee also matters on a small card. A ₹600 bill paid late now costs ₹500 + GST, almost as much as the bill itself.
Eligibility & Documents Required
PNB asks for an annual income of ₹2.5 lakh or more. Its product page does not publish an age band or a minimum credit score, so ask PNB about the full criteria before applying.
Expect to submit PAN, address proof and income proof. You may be asked to complete video KYC, and existing PNB customers can see a pre-qualified offer on the card portal.
Pros & Cons
| Pros | Cons |
|---|---|
| No joining or annual fee, with no conditions | Only 0.25% back in reward points |
| Low ₹2.5 lakh income requirement | No lounge access and no welcome bonus |
| Free add-on cards | ₹99 + GST fee on every redemption |
| Points last 3 years | Cash withdrawal fee rises to a ₹400 minimum |
PNB Visa Classic vs Competitors
| Feature | PNB Visa Classic | PNB RuPay Platinum | PNB Visa Gold |
|---|---|---|---|
| Annual fee | Nil | ₹500, waived on one use every quarter | ₹300, waived on conditions |
| Reward rate | 1 point per ₹100 | 1 point per ₹100 | 1 point per ₹100 |
| Lounges | None | 2 domestic a quarter, 2 abroad a year | None |
| UPI payments | No | Yes | No |
| Credit limit | ₹10,000 to ₹1 lakh | ₹10,000 to ₹5 lakh | ₹50,000 to ₹5 lakh |
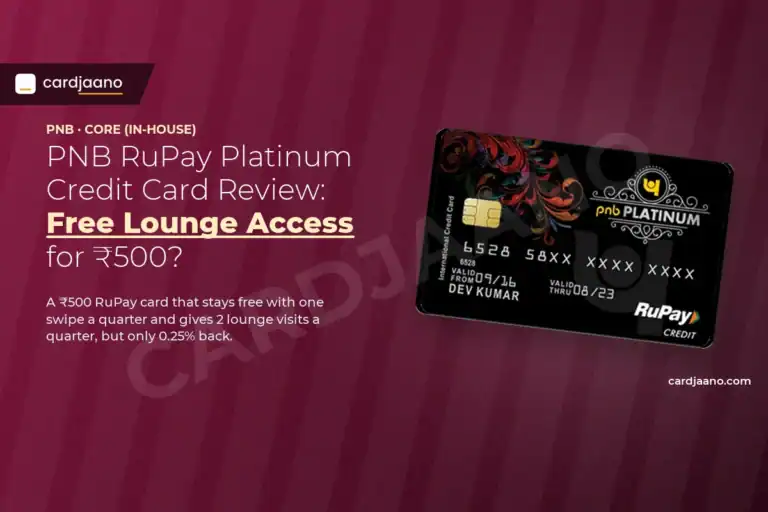
Fees are plus GST. The PNB RuPay Platinum earns the same points, adds lounge visits and UPI, and stays free if you use it once a quarter. For most people it is the better PNB entry card.
Visa Classic wins only if you want a card with no fee rule to track at all, or if you specifically need a Visa card for a merchant that does not accept RuPay.
How to Apply
Apply on PNB’s credit card portal through the online or paperless application, or visit a PNB branch with the application form. Pre-qualified customers may see an offer after logging in.
Fill in your income and KYC details, complete video KYC if asked, and track your application status on the same portal.
Frequently Asked Questions
Is the PNB Visa Classic Credit Card lifetime free?
Yes. PNB charges no joining fee and no annual fee on the primary card or add-on cards, and there is no spend condition attached.
What is the minimum income for PNB Visa Classic?
₹2.5 lakh a year. Approval and the credit limit, which ranges from ₹10,000 to ₹1 lakh, depend on PNB’s assessment of your profile.
How much is a PNB reward point worth?
₹0.25. You need at least 1,000 points to redeem, and each redemption carries a ₹99 + GST fee.
Does PNB Visa Classic give lounge access?
No. The product page lists both airport and railway lounge access as nil. PNB’s RuPay Platinum card is the cheapest PNB card with lounge visits.
What is the interest rate on PNB Visa Classic?
2.95% a month, or 35.89% a year, on any balance you carry forward. Pay the full bill by the due date to enjoy the 20 to 50 day interest-free period.
Bottom Line
Get the PNB Visa Classic Credit Card if you want a free first card to build a credit score, bank with PNB, and plan to pay in full every month. It costs nothing to hold, and the low income bar makes approval more likely.
Skip it if you want rewards that add up, because 0.25% back is among the lowest in the market and the ₹99 redemption fee eats into it. Skip it too if you want UPI or lounge visits, where PNB’s own RuPay Platinum does more for a fee that is easy to waive.
Never use it for cash, and avoid it abroad, where the 3.5% markup applies.
Fees and features are as of October 2026, including PNB’s charges effective 1 November 2026. Check PNB’s site before applying.