HDFC Bharat Credit Card Review
At a Glance
| Joining Fee | ₹500 + GST (₹590 all-in) |
| Annual Fee | ₹500 + GST (₹590 all-in), waived on ₹50,000 of spends a year |
| Best Suited For | Existing holders with steady fuel, grocery, bill and IRCTC spends |
| Reward Type | 5% cashback in select categories, capped at ₹150 a month |
| New applications | Closed |
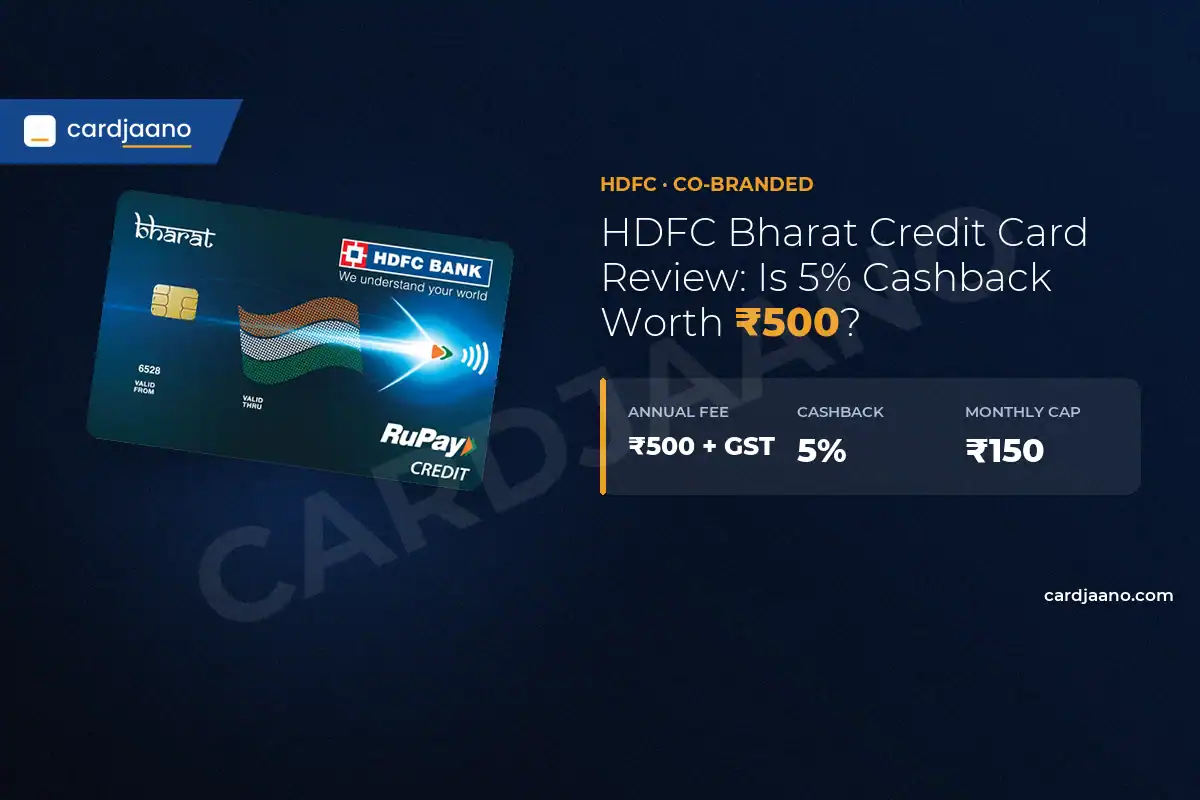
The HDFC Bank Bharat Credit Card, also sold as the Bharat CashBack Card, was built for everyday household spending.
It pays 5% cashback on fuel, groceries, bill payments, mobile recharges, IRCTC tickets and HDFC’s own PayZapp, EasyEMI and SmartBuy, with all of that capped at ₹150 a month combined.
The fee is ₹500 + GST. HDFC’s own FAQ says it is not accepting new applications, so this page is mainly for people who already hold the card.
The key question for them is simple: does a maximum of ₹1,800 a year in cashback justify keeping it, given how and when that cashback can actually be redeemed?
Rewards & Benefits
Reward rate and earn structure
| Spend category | Cashback |
|---|---|
| PayZapp, EasyEMI and SmartBuy | 5% |
| IRCTC ticket bookings | 5% |
| Fuel, grocery, bill payments, mobile recharge | 5% |
| Combined cap for all the above | ₹150 a month |
| Flights, hotels and vouchers via SmartBuy | Up to 10% (SmartBuy offer terms apply) |
The 5% rate is generous but the cap is tight. You hit the ₹150 monthly ceiling after just ₹3,000 of eligible spends, and nothing in those categories earns more after that. Over a full year the most this card can return in these categories is ₹1,800.
HDFC decides eligibility by the Merchant Category Code (MCC) of each transaction, and only the RuPay MCCs it marks as eligible earn 5%. Spends outside fuel, groceries, IRCTC and recharges earn no cashback.
Wallet loading, rent and government payments earn nothing, and recharges done at mobile shops or bundled with a phone purchase are excluded.
Redemption and point value
Cashback is credited as Reward Points in the next statement, and 1 Reward Point = ₹1. So ₹150 of cashback shows up as 150 points. Redeeming them is where this card gets awkward:
| Rule | What HDFC publishes |
|---|---|
| Minimum for cashback redemption | ₹2,500 for the Bharat card (MITC) |
| Monthly redemption cap | 3,000 points a month |
| Redemption on products or vouchers | Points can cover up to 70% of the value |
| Cashback redemption charge | ₹50 per request (MITC) |
| Point expiry | 2 years from accumulation |
Here is the arithmetic that matters. At the maximum ₹150 a month, it takes 17 months to reach the ₹2,500 needed to redeem against your statement.
If you earn less than the cap, points start expiring after two years before you ever get there. Check your points balance in MyCards every few months and redeem as soon as you cross ₹2,500.
Fuel and PayZapp benefits
You get a 1% fuel surcharge waiver on fuel transactions between ₹400 and ₹5,000, up to ₹250 per statement cycle.
Linking the card to PayZapp adds extra cashback and Reward Points on bill payments and recharges, an offer of ₹1,000 cashback on in-app shopping across 200+ brands, and OTP-free “Swipe to Pay”.
HDFC does not publish the rate for the extra PayZapp rewards, so treat that as an offer rather than a fixed benefit.
Fees & Charges
| Item | Charge |
|---|---|
| Joining fee | ₹500 + GST |
| Annual fee | ₹500 + GST |
| Renewal waiver | Spend ₹50,000 in a year (MITC) |
| Interest (finance charge) | 3.75% a month, 45% a year (MITC) |
| Cash advance | 2.5% of the amount, minimum ₹500 |
| Fuel surcharge waiver | 1% on ₹400 to ₹5,000, max ₹250 per cycle |
| Rent payments | 1% fee, capped at ₹4,999 per transaction |
| Utility spends | 1% fee on the total above ₹50,000 a month |
| Wallet loads | 1% fee on the total above ₹10,000 a month |
| Late payment | Slab-based; see the Schedule of Charges in HDFC’s MITC |
| GST | 18% on all fees, interest and charges |
The ₹500 renewal fee goes away if you spend ₹50,000 in a card year, about ₹4,170 a month. The waiver threshold appears in HDFC’s MITC fee table rather than on the product page, which only says the fee can be offset with reward points.
The surprise for most holders is the inactivity rule. HDFC can cancel the card if it is not used for six months in a row, after notice by email, phone or post. A card kept only for IRCTC bookings a few times a year is at risk.
Eligibility & Documents Required
HDFC does not list eligibility for the Bharat card because it is not accepting new applications. Existing holders do not need to do anything to keep it.
If you want a different HDFC card, use the bank’s Credit Card Upgrade service, where HDFC will reassess your income and repayment history.
Keep PAN, address proof and recent salary slips or ITR ready, as HDFC asks for these on any fresh card.
Pros & Cons
| Pros | Cons |
|---|---|
| 5% back on fuel, grocery, bills, recharge and IRCTC | Combined cap of only ₹150 a month |
| 1 point = ₹1, simple to value | ₹2,500 minimum before cashback redemption |
| Low ₹500 fee, waived on ₹50,000 a year | No cashback outside the listed categories |
| Fuel surcharge waiver up to ₹250 a cycle | Closed to new applicants |
Bharat Credit Card vs Competitors
Within HDFC, the MoneyBack+ card carries the same ₹500 fee and the same ₹50,000 renewal waiver in the MITC, but uses Reward Points instead of a flat 5% bucket.
The Millennia card shares the Bharat card’s 3,000-point monthly redemption cap but is still open to new applicants.
If you mainly want cashback on bills and groceries without a ₹150 ceiling, compare both on HDFC’s site before deciding.
How to Apply
You cannot apply for the Bharat card today. HDFC states it is currently not accepting new applications and points visitors to its other credit cards. If you already hold it, manage limits, online use and international use through NetBanking, the MobileBanking app, MyCards, PayZapp or WhatsApp Banking. To switch cards, use HDFC’s Credit Card Upgrade page.
Frequently Asked Questions
What is the annual fee of the HDFC Bharat Credit Card?
₹500 + GST, which is ₹590 all-in. HDFC’s MITC waives it when you spend ₹50,000 in a year.
How much cashback can I earn on the Bharat card?
A maximum of ₹150 a month across all the 5% categories combined. That caps the card at ₹1,800 a year.
Is the Bharat card the same as the Bharat CashBack card?
Yes. HDFC’s own FAQ says the Bharat Credit Card is often called the Bharat CashBack Card.
When can I redeem Bharat card cashback?
Once you have at least ₹2,500 for a cashback redemption, according to HDFC’s MITC. Each request costs ₹50, and points expire two years after you earn them.
Does the Bharat card give cashback on rent or wallet loads?
No. Rent, wallet loading and government transactions earn nothing. HDFC also charges a 1% fee on rent payments.
Can I still apply for the HDFC Bharat Credit Card?
No. HDFC is not accepting new applications. Existing holders keep the card and its benefits.
Bottom Line
Keep the Bharat card if you already have it, put at least ₹3,000 a month of fuel, grocery, bill and IRCTC spends on it, and cross ₹50,000 a year so the fee is waived.
In that case you earn up to ₹1,800 a year for nothing. Skip it, or upgrade, if your category spends are well below ₹3,000 a month, if you would struggle to reach the ₹2,500 redemption minimum before points expire, or if you pay the ₹590 renewal fee for a card you rarely use. New applicants cannot get it.