IDFC FIRST Millennia Credit Card Review
At a Glance
| Joining Fee | Nil |
| Annual Fee | Nil, lifetime free |
| Best Suited For | Young earners who eat out, travel a little and want a free card with zero forex markup |
| Reward Type | IDFC FIRST Reward Points, 1 point = ₹0.25 |
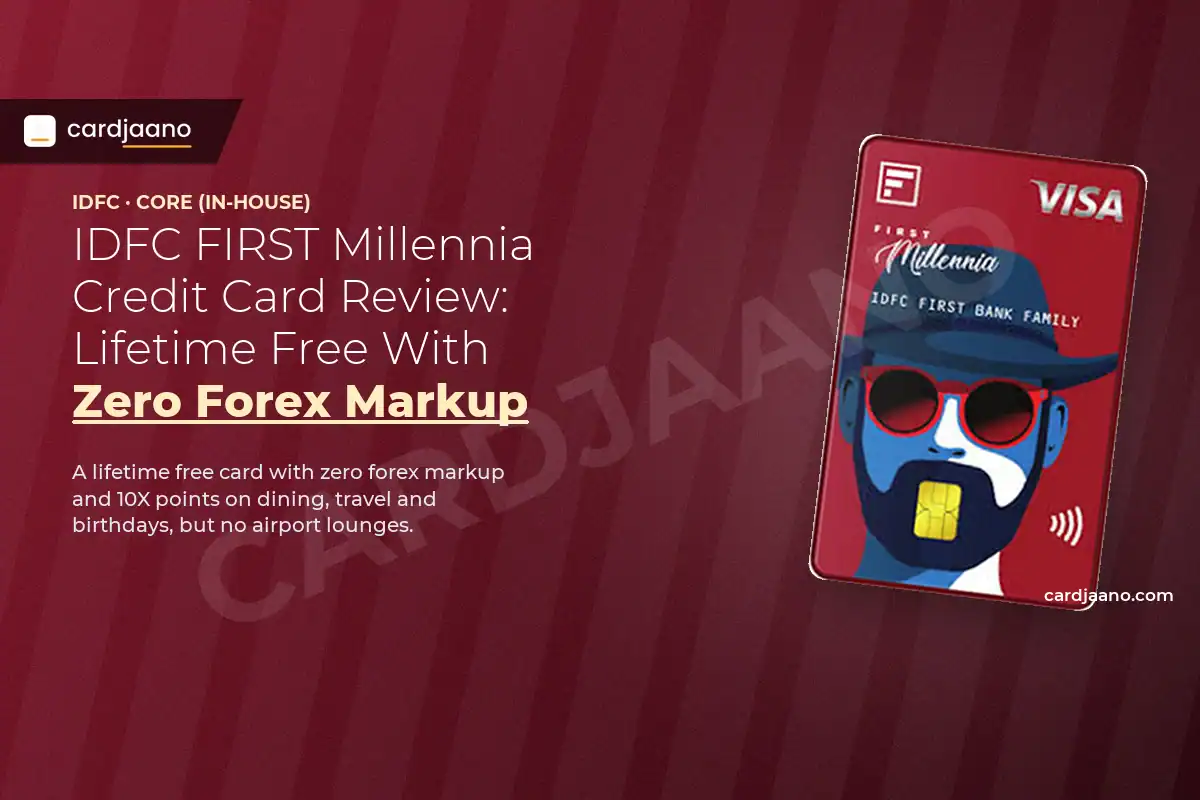
The IDFC FIRST Millennia Credit Card is a lifetime free card aimed at first jobbers and young professionals with an income of ₹3 lakh a year or more.
It never charges a joining or annual fee, it has no markup on foreign currency spends, and it pays its best reward rate, 10X points, on dining, travel, international spends and anything you buy on your birthday.
The catch is that one point is worth only ₹0.25, so the everyday earn rate is modest, and there is no airport lounge access at all. This review puts a rupee figure on every part of it.
Rewards & Benefits
Reward rate and earn structure
IDFC FIRST Bank counts rewards in multiples. 1X means 1 Reward Point for every ₹200 spent, and each point is worth ₹0.25.
| Spend | Points per ₹200 | Value back |
|---|---|---|
| Dining, travel, international spends, and all spends on your birthday | 10 (10X) | 1.25% |
| All other eligible spends, including online shopping and groceries | 3 (3X) | 0.375% |
| Utility bills, insurance premiums, railway spends, FASTag recharges | 1 (1X) | 0.125% |
| Fuel, EMI transactions, cash withdrawals, fees | 0 | Nil |
IDFC FIRST Bank’s page publishes no monthly cap on the 10X rate; the only limit it states is that points are earned on spends up to your credit limit in each billing cycle, and anything beyond that earns nothing.
Points stay valid for 24 months. If you miss the Minimum Amount Due, you earn no points for that cycle and any already posted are reversed.
Redemption and point value
You can use points through “pay with points” at the payment gateway on online purchases, at some partner stores, or for flights and hotels in the FIRST Rewards Gallery section of the IDFC FIRST Bank app, all at ₹0.25 a point.
Every redemption carries a ₹99 + GST fee (₹116.82 all-in). That fee eats the whole value of about 467 points, so redeem in large batches rather than every month.
Booking flights and hotels through the FIRST Rewards Gallery adds bonus points on top of the 10X travel rate: 10% extra on flights and 20% extra on hotels, capped at 8,000 bonus points a calendar month.
Welcome benefits
| Benefit | Condition |
|---|---|
| ₹500 gift voucher from a choice of brands | Spend ₹5,000 within 30 days of card generation (UPI, add-on, wallet load, EMI and cash withdrawals do not count) |
| 5% cashback up to ₹1,000 | On your first EMI conversion within 30 days of card generation |
Travel, lifestyle and protection
| Benefit | Allowance |
|---|---|
| Railway lounges | 4 visits a quarter, unlocked for next month by spending ₹20,000 in the current calendar month |
| Airport lounges | Not offered |
| Movies | 25% off up to ₹100 on District by Zomato, once a month, if you made at least one transaction the previous month |
| Fuel surcharge waiver | 1% on fuel spends of ₹200 to ₹5,000, up to ₹200 a month |
| Roadside assistance | Worth ₹1,399, up to 4 times a year |
| Personal accident cover | ₹2,00,000 |
| Lost card liability | ₹25,000 |
Both insurance covers apply only if you used the card at least once in the previous 30 days.
Fees & Charges
| Item | Charge |
|---|---|
| Joining and annual fee | Nil |
| Add-on card | ₹499 + GST joining and ₹499 + GST a year, per card |
| Image personalised card | ₹499 + GST joining and ₹499 + GST a year |
| FIRST Digital RuPay card for UPI | ₹199 + GST joining and ₹199 + GST a year |
| Foreign currency markup | Nil |
| Interest on purchases and balances | 0.71% to 3.85% a month, 8.5% to 46.2% a year, set by your credit profile |
| Overdue interest if Minimum Amount Due is missed | 3.99% a month, 47.88% a year |
| Interest-free period | Up to 45 days |
| Cash withdrawal | ₹199 + GST per transaction, interest free for up to 45 days |
| Late payment | 15% of the Total Amount Due less payments made, minimum ₹100, maximum ₹1,300 |
| Over-limit (opt-in only) | 2.5% of the over-limit amount, minimum ₹550 |
| Payment return | 2% of the payment, minimum ₹500 |
| Reward redemption | ₹99 + GST per redemption |
| GST | 18% on fees, interest and charges |
There is no fee to waive, so the only spending targets that matter are the ₹5,000 in 30 days for the welcome voucher and ₹20,000 a month if you want the railway lounges.
The charge that catches people out is the interest range. IDFC FIRST Bank advertises rates from 8.5% a year, but your actual rate depends on your credit history and can be as high as 46.2%, rising to 47.88% if you miss the minimum payment.
Check the rate printed on your welcome letter before you carry any balance. Cash withdrawals are unusually cheap here: a flat ₹199 + GST with no interest for up to 45 days, though you can take out at most ₹10,000 per transaction.
Eligibility & Documents Required
IDFC FIRST Bank asks for an annual income of ₹3 lakh or more. Age, employment and credit score are assessed under the bank’s internal policy during the application, so check the full criteria on the issuer’s site.
The process is digital: you share PAN and Aadhaar details, provide income proof if asked, and complete video KYC. If you already hold an unsecured IDFC FIRST credit card, the new card shares that card’s credit limit.
Pros & Cons
| Pros | Cons |
|---|---|
| Lifetime free, no spend target to keep it free | No airport lounge access |
| Zero forex markup on international spends | 3X on everyday spends is only 0.375% back |
| 10X on dining, travel, international and birthday spends | ₹99 + GST fee on every redemption |
| Cash withdrawals at ₹199 + GST with 45 days interest free | Railway lounges need ₹20,000 of spend a month |
IDFC FIRST Millennia vs Competitors
| Card | Annual fee | Fee waived at | Best for |
|---|---|---|---|
| IDFC FIRST Millennia | Nil | Always free | Dining, travel and forex |
| HDFC Millennia | ₹1,000 + GST | ₹1 lakh a year | Cashback on Amazon, Flipkart, Swiggy and Zomato |
| SimplyClick SBI Card | ₹499 + GST | ₹1 lakh a year | Rewards at SBI’s online partner brands |
If most of your spending goes to a handful of shopping apps, the HDFC and SBI cards return more on those brands.
The IDFC card wins when your spending is spread across restaurants, trips and foreign websites, and when you never want to track a fee waiver target.
How to Apply
Apply from the FIRST Millennia page on IDFC FIRST Bank’s website or app. Enter your PAN, income and employment details, check the credit limit and interest rate offered, and finish with video KYC.
A virtual card is available in the app once the card is issued. Plan ₹5,000 of eligible card spends within 30 days to claim the ₹500 welcome voucher.
Frequently Asked Questions
Is the IDFC FIRST Millennia Credit Card really lifetime free?
Yes. The joining fee and annual fee are both nil, with no spend condition. Add-on cards, personalised card designs and the UPI RuPay card do carry their own fees.
Does IDFC FIRST Millennia give airport lounge access?
No. It offers 4 railway lounge visits a quarter, unlocked by spending ₹20,000 in the previous calendar month, but no domestic or international airport lounges.
What is the minimum salary for IDFC FIRST Millennia?
₹3 lakh a year. Final approval and your credit limit depend on IDFC FIRST Bank’s assessment of your credit profile.
What is the forex markup on IDFC FIRST Millennia?
Zero. To keep it that way, always pay in the local currency abroad, because a merchant’s Indian rupee conversion (dynamic currency conversion) can add its own charge.
How much is a Millennia reward point worth?
₹0.25. With a ₹99 + GST fee on each redemption, it pays to collect a few thousand points before you redeem.
Bottom Line
Get the IDFC FIRST Millennia Credit Card if you want a free card that you will never have to justify, especially if you eat out, book trips or buy from foreign websites, where it earns 1.25% back with no forex markup.
It also makes a good second card to carry abroad. Skip it if you want airport lounges, or if most of your spending is everyday online shopping and bills, where 0.375% back or less is weak. Big online shoppers will get more from a co-branded or cashback card.
2 Comments